Exhibit 99.2 Cleansing Materials 1 September 2026
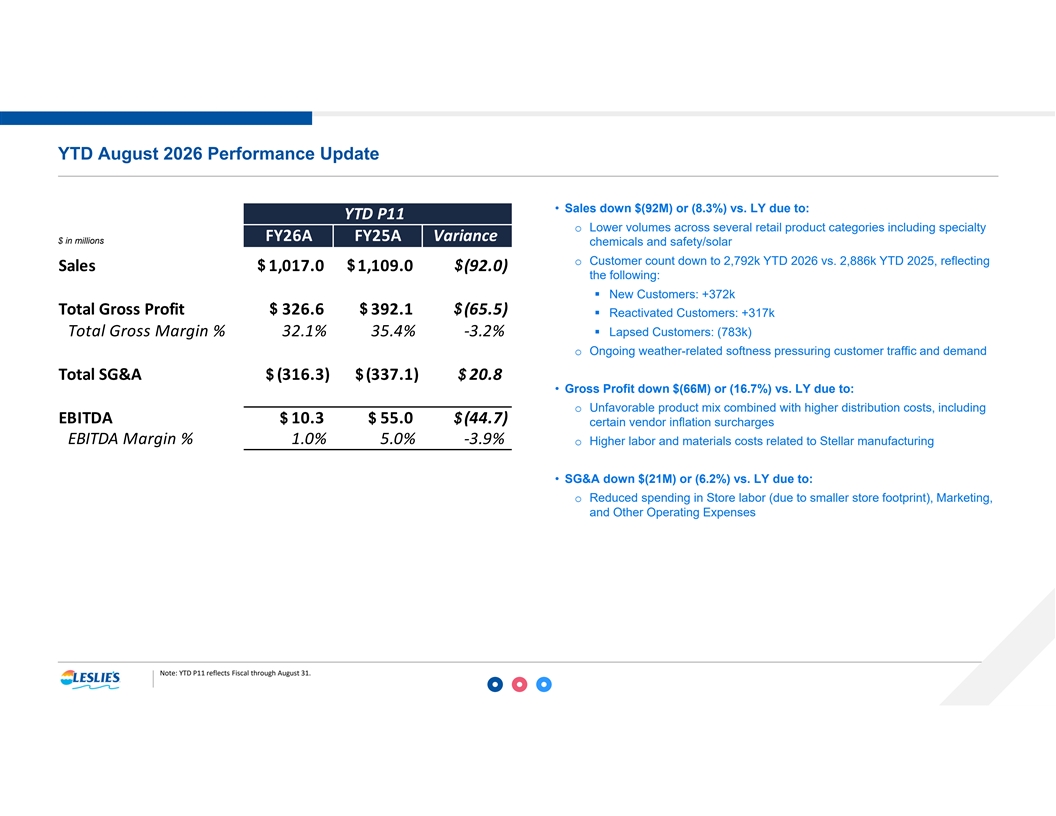
YTD August 2026 Performance Update • Sales down $(92M) or (8.3%) vs. LY due to: YTD P11 o Lower volumes across several retail product categories including specialty FY26A FY25A Variance $ in millions chemicals and safety/solar o Customer count down to 2,792k YTD 2026 vs. 2,886k YTD 2025, reflecting $$ $ Sales 1,017.0 1,109.0 (92.0) the following: § New Customers: +372k Total Gross Profit $$ 326.6 392.1 $ (65.5) § Reactivated Customers: +317k Total Gross Margin % 32.1% 35.4% -3.2%§ Lapsed Customers: (783k) o Ongoing weather-related softness pressuring customer traffic and demand Total SG&A $$ (316.3) (337.1) $ 20.8 • Gross Profit down $(66M) or (16.7%) vs. LY due to: o Unfavorable product mix combined with higher distribution costs, including EBITDA $ 10.3 $ 55.0 $(44.7) certain vendor inflation surcharges EBITDA Margin % 1.0% 5.0% -3.9% o Higher labor and materials costs related to Stellar manufacturing • SG&A down $(21M) or (6.2%) vs. LY due to: o Reduced spending in Store labor (due to smaller store footprint), Marketing, and Other Operating Expenses Note: YTD P11 reflects Fiscal through August 31.
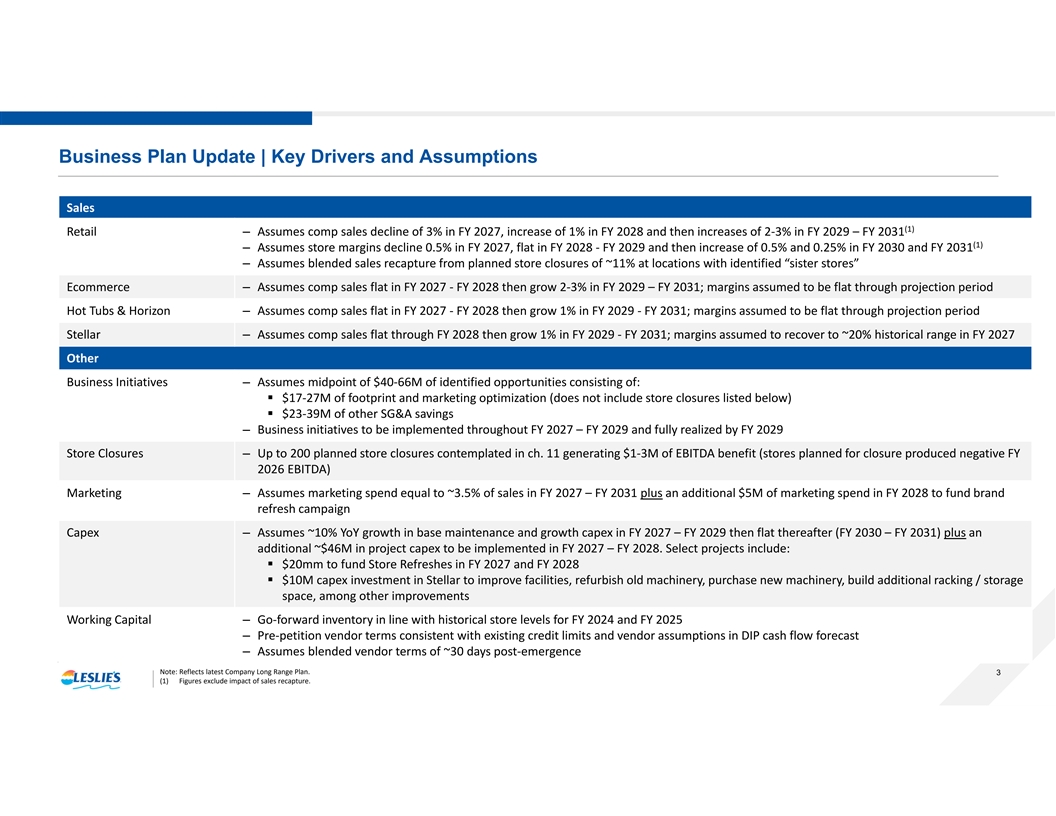
Business Plan Update | Key Drivers and Assumptions Sales (1) Retail – Assumes comp sales decline of 3% in FY 2027, increase of 1% in FY 2028 and then increases of 2-3% in FY 2029 – FY 2031 (1) – Assumes store margins decline 0.5% in FY 2027, flat in FY 2028 - FY 2029 and then increase of 0.5% and 0.25% in FY 2030 and FY 2031 – Assumes blended sales recapture from planned store closures of ~11% at locations with identified “sister stores” Ecommerce – Assumes comp sales flat in FY 2027 - FY 2028 then grow 2-3% in FY 2029 – FY 2031; margins assumed to be flat through projection period Hot Tubs & Horizon – Assumes comp sales flat in FY 2027 - FY 2028 then grow 1% in FY 2029 - FY 2031; margins assumed to be flat through projection period Stellar – Assumes comp sales flat through FY 2028 then grow 1% in FY 2029 - FY 2031; margins assumed to recover to ~20% historical range in FY 2027 Other Business Initiatives – Assumes midpoint of $40-66M of identified opportunities consisting of: § $17-27M of footprint and marketing optimization (does not include store closures listed below) § $23-39M of other SG&A savings – Business initiatives to be implemented throughout FY 2027 – FY 2029 and fully realized by FY 2029 Store Closures – Up to 200 planned store closures contemplated in ch. 11 generating $1-3M of EBITDA benefit (stores planned for closure produced negative FY 2026 EBITDA) Marketing – Assumes marketing spend equal to ~3.5% of sales in FY 2027 – FY 2031 plus an additional $5M of marketing spend in FY 2028 to fund brand refresh campaign Capex – Assumes ~10% YoY growth in base maintenance and growth capex in FY 2027 – FY 2029 then flat thereafter (FY 2030 – FY 2031) plus an additional ~$46M in project capex to be implemented in FY 2027 – FY 2028. Select projects include: § $20mm to fund Store Refreshes in FY 2027 and FY 2028 § $10M capex investment in Stellar to improve facilities, refurbish old machinery, purchase new machinery, build additional racking / storage space, among other improvements Working Capital – Go-forward inventory in line with historical store levels for FY 2024 and FY 2025 – Pre-petition vendor terms consistent with existing credit limits and vendor assumptions in DIP cash flow forecast – Assumes blended vendor terms of ~30 days post-emergence Note: Reflects latest Company Long Range Plan. 3 (1) Figures exclude impact of sales recapture.
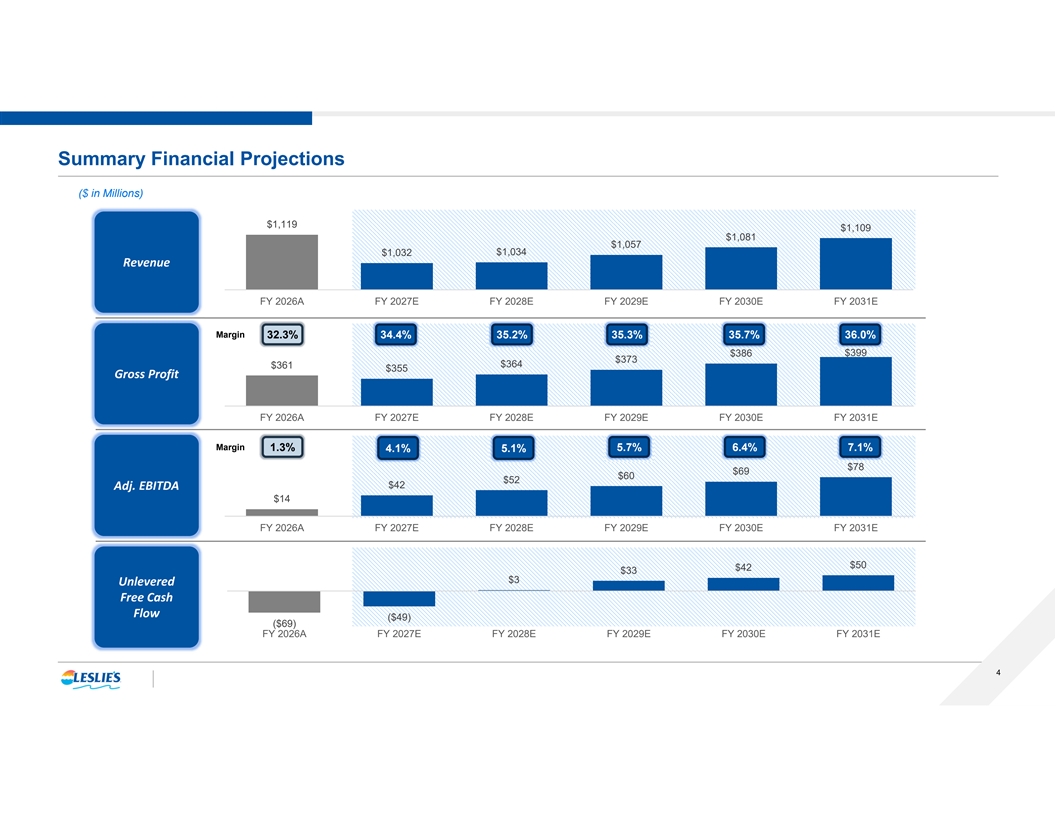
Summary Financial Projections ($ in Millions) $1,119 $1,109 $1,081 $1,057 $1,032 $1,034 Revenue FY 2026A FY 2027E FY 2028E FY 2029E FY 2030E FY 2031E Margin 32.3% 34.4% 35.2% 35.3% 35.7% 36.0% $399 $386 $373 $364 $361 $355 Gross Profit FY 2026A FY 2027E FY 2028E FY 2029E FY 2030E FY 2031E Margin 1.3% 5.7% 6.4% 7.1% 4.1% 5.1% $78 $69 $60 $52 $42 Adj. EBITDA $14 FY 2026A FY 2027E FY 2028E FY 2029E FY 2030E FY 2031E $50 $42 $33 $3 Unlevered Free Cash Flow ($49) ($69) FY 2026A FY 2027E FY 2028E FY 2029E FY 2030E FY 2031E 4